Self-employed home loans · Sydney
Self-employed home loans,with your income read properly.
Sole trader, contractor, company director or trust income? Lenders read business income from your tax returns, financials and BAS, and each lender reads them differently. Rohan Manokaran is a credit representative and Chartered Accountant, so your application is prepared by someone who understands the numbers behind it.
- Credit Representative
- CR 565110, authorised under ACL 561324 held by Loans Only Pty Ltd
- Chartered Accountant
- CA ANZ member 266544
- Complaints body
- AFCA member 111743 (individual) · 111742 (company)
- Meetings
- Zoom and phone across Sydney, or a visit to our Cherrybrook office.
Who we help
Self-employed lending, in all its shapes.
Sole traders and contractors
ABN income, day-rate contracts and income that moves from year to year, presented the way lenders assess it.
Company directors
Salary, director fees and company profits. We work out which figures a lender may count and document them properly.
Trust income
Distributions from a family or unit trust narrow the lender list and widen the paperwork. We know what lenders tend to ask for.
Low-doc and alt-doc
Where your latest returns don’t show where your business is now, some lenders accept alternative evidence such as BAS or an accountant’s declaration. Low doc still means evidence.
ATO debt or a payment plan
Owing the ATO doesn’t always rule out a home loan. Some lenders consider paying out ATO debt through a refinance, case by case, where repayment history and serviceability are acceptable. Turning tax debt into home-loan debt can cost more overall, and we explain that first.
Refinancing and investing
Already have a loan? We review whether a refinance or an investment purchase fits how your business income is assessed.
The difference
A tax return is only part of the picture. Rohan reads the rest.
Add-backs understood
Depreciation, one-off expenses, director salaries and trust distributions can change what a lender counts. Rohan knows what sits behind each figure.
Matched to lender policy
Lender policy on self-employed income varies. We shortlist lenders from our panel whose policy fits how your income is earned and documented.
Straight answers
Understanding your numbers can’t promise a bigger loan or an approval. It means fewer surprises once the lender looks.
How it works
Three steps. One person.
Your income, first
Tell us about your business, how you’re paid and what you’re planning. A scoping conversation, not an approval.
Records and lender policy
We review the records you have (returns, financials, BAS) and the lender-policy questions they raise. Please don’t send documents through the enquiry form.
Options to settlement
We discuss suitable options from our lender panel and, if you go ahead, manage the application through to settlement.
Before your call
What lenders usually ask for.
Every lender is different, but these come up again and again for self-employed borrowers. Rough answers are fine for the first call.
- Personal and business tax returns, with notices of assessment, for the last one or two years
- Business financial statements: profit and loss, and balance sheet
- Recent BAS and business bank statements, where a lender asks for them
- How your business is set up: sole trader, partnership, company or trust
- Existing loans, any ATO payment plan, and your deposit or equity
Please don’t send documents through the enquiry form. Rohan will explain what’s needed and how to send it.
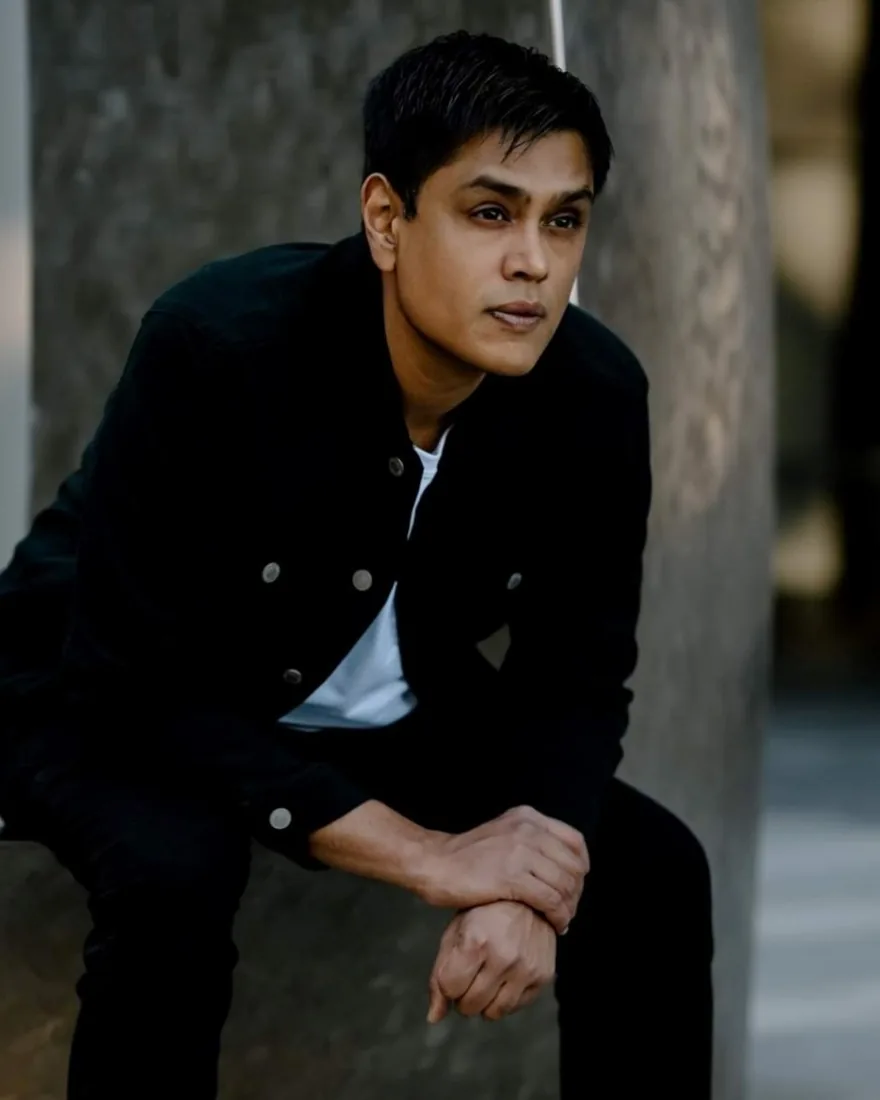
Who you’ll deal with
Rohan Manokaran
Rohan is a Chartered Accountant and Credit Representative 565110, authorised under Australian Credit Licence 561324 held by Loans Only Pty Ltd. He runs Eternity Mortgage Solutions from Cherrybrook, alongside his accounting practice, Eternity Group Accountants.
Most meetings happen by Zoom or phone. You’re also welcome to visit the Cherrybrook office, or Rohan can come to you, and we’ll confirm the meeting location before travelling.
Mortgage broking and accounting are separate engagements. You can keep your existing accountant, and any coordination with them happens only with your consent.
Before we speak
Common questions
Can I get a home loan with only one year of tax returns?
Some lenders consider shorter trading histories or alternative evidence, depending on your circumstances. We check the relevant lender policies first. No exception can be promised in advance.
What does low doc actually mean?
Some lenders assess income using alternative evidence, such as BAS or an accountant’s declaration, instead of full tax returns. It isn’t a no-documentation loan: the lender still assesses your income, expenses and debts, and rates, fees and deposit requirements can differ.
Can I get a home loan if I owe the ATO?
It depends on the lender and your circumstances. Some lenders consider borrowers with ATO debt or a payment plan, and some allow the debt to be paid out at settlement as part of a refinance. They usually ask why the debt built up and how it will be managed from here. Rolling tax debt into a home loan can cost more overall, so we look at that trade-off with you first. No outcome can be promised in advance.
How are mortgage brokers paid?
In most residential lending scenarios, the lender pays broker commission. If a borrower-paid fee applies, it will be disclosed in writing before you proceed, including in any required Credit Quote or credit disclosure document. Our remuneration, lender panel and any conflicts of interest are explained in our Credit Guide.
Do I need to move my accounting work to you?
No. Lending and accounting are separate engagements, and you can keep your existing accountant.
My bank said no. Can you help?
A previous decline can show which facts or policies need attention. Another application isn’t automatically suitable or successful, so we look at your circumstances before suggesting a next step.
Your business is complex. Your loan conversation doesn’t have to be.
Call Rohan directly, or leave your number and he’ll call you back.