Mortgage broker · Castle Hill · Hills District
Mortgage broker in the Hills District.Buying, refinancing or reviewing your loan?
Talk to Rohan Manokaran, a credit representative and Chartered Accountant based in Cherrybrook, about buying a home, refinancing or restructuring your loan. With rates rising again, you’ll see the costs and trade-offs of each option before you decide.
Based in Cherrybrook and working with borrowers across Castle Hill, Kellyville, Baulkham Hills, Norwest, Bella Vista and Hornsby, and the rest of greater Sydney by Zoom or phone.
- Credit Representative
- CR 565110, authorised under ACL 561324 held by Loans Only Pty Ltd
- Chartered Accountant
- CA ANZ member 266544
- Complaints body
- AFCA member 111743 (individual) · 111742 (company)
- Meetings
- Zoom, phone, or a visit to our Cherrybrook office. Home visits welcome.
Ways we can help
Ways to ease the pressure.
Refinance your loan
We compare your current rate, fees and features with options on our lender panel. Switching isn’t always worth it once the costs are counted, so we show you both sides.
Lower your monthly repayments
Extending your loan term can reduce repayments now. You’ll pay more interest over the life of the loan, and we show you both numbers before you decide.
Roll expensive debts into one
Car loans, credit cards and personal loans can sometimes be consolidated into your home loan. It can cut what goes out each month, but it turns short-term debt into long-term debt and can cost more overall.
Lock in certainty
Fixing all or part of your loan for two or three years makes repayments predictable. Fixed loans can carry break costs and fewer features, and we explain them first.
When your bank says no
Where a bank’s policy doesn’t fit, a non-bank lender on our panel may. Criteria, rates and fees vary, and every application is assessed by the lender.
Still buying?
Borrowing power has fallen with each rise. We work out what lenders will allow now and manage the application through to settlement.
The difference
Your mortgage broker is also a Chartered Accountant.
Your whole budget, read properly
Payslips, tax returns, debts and business financials, read the way a lender will read them, before the application goes in.
Self-employed? One stop.
Rohan can get your tax returns, BAS and profit and loss in order before a lender sees them, under a separate accounting engagement.
One person, start to finish
You deal with Rohan directly, from the first call through to settlement, rather than being passed between departments.
How it works
Three steps. One person.
A conversation
We look at your repayments, income, debts and plans. It’s a scoping conversation, not a loan approval.
Options, with the trade-offs
We compare suitable options from our lender panel and show you the costs, including switching costs, before anything is decided.
Application to settlement
With your agreement and the required disclosures, we lodge with the lender you choose and keep you updated through to settlement.
Before your call
What helps to have handy.
You don’t need everything for the first conversation. A rough idea of these speeds things up.
- Your current home loan statement, and any fixed-rate end date
- Your income: recent payslips, or your last two tax returns if you’re self-employed
- Car loans, credit cards and personal loans, with their balances and limits
- Roughly what your household spends each month, as lenders will ask
- Buying? Your deposit and the suburbs you have in mind
Please don’t send documents through the form. Rohan will explain what’s needed and how to send it.
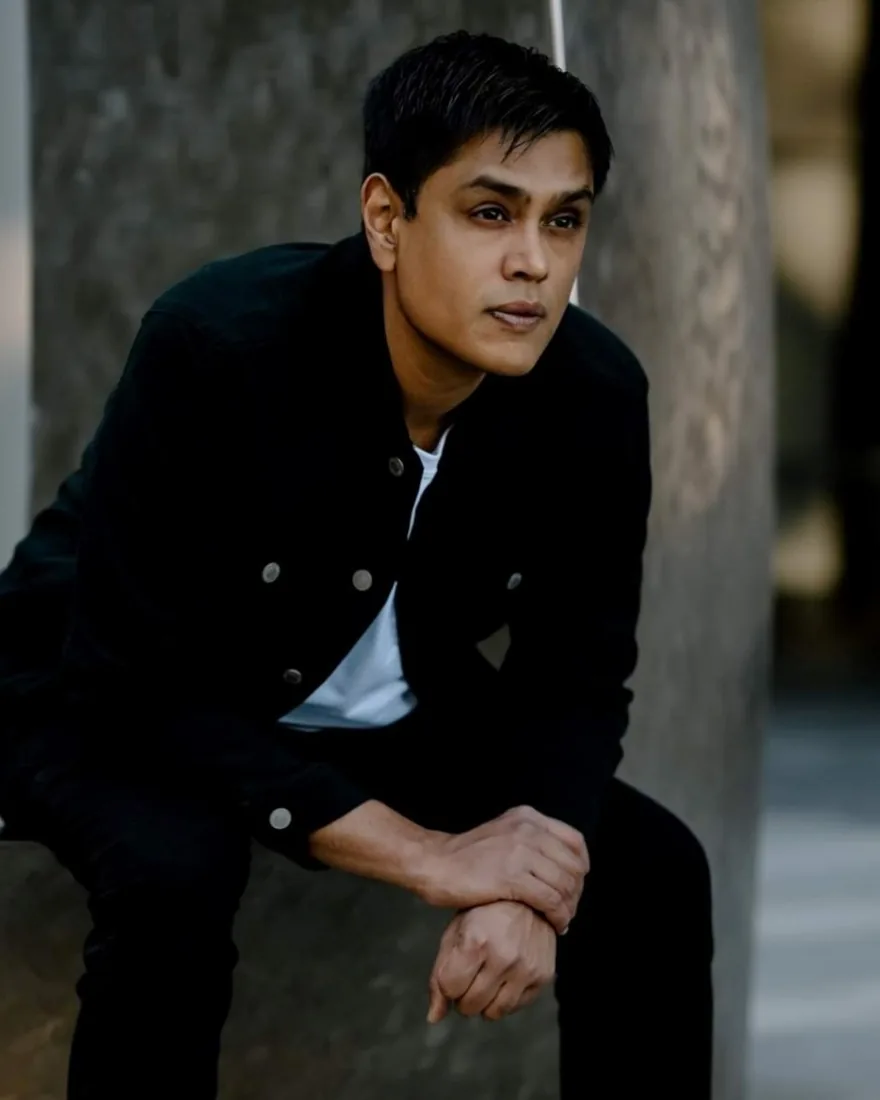
Who you’ll deal with
Rohan Manokaran
Rohan is a Chartered Accountant and Credit Representative 565110, authorised under Australian Credit Licence 561324 held by Loans Only Pty Ltd. He runs Eternity Mortgage Solutions from Cherrybrook, alongside his accounting practice, Eternity Group Accountants.
Most meetings happen by Zoom or phone. You’re also welcome to visit the Cherrybrook office, or Rohan can come to you, and we’ll confirm the meeting location before travelling.
Mortgage broking and accounting are separate engagements. You don’t need to change accountants to talk about your home loan.
Before we speak
Common questions
Will refinancing definitely lower my repayments?
Not always. It depends on your current loan, the costs of switching and what lenders will offer you. We show you the numbers, including switching costs, before you decide.
Is extending my loan term a good idea?
It can ease your monthly repayments, but you’ll pay more interest over the life of the loan. Whether it suits you depends on your circumstances and plans, and we talk it through with you.
Should I fix my rate?
Fixing gives you certainty on repayments for a set period, but can mean break costs and fewer features. We explain the trade-offs so you can decide. We don’t predict where rates will go.
How are mortgage brokers paid?
In most residential lending scenarios, the lender pays broker commission. If a borrower-paid fee applies, it will be disclosed in writing before you proceed, including in any required Credit Quote or credit disclosure document. Our remuneration, lender panel and any conflicts of interest are explained in our Credit Guide.
Can you guarantee my loan will be approved?
No. Every application is assessed by the lender, and eligibility, lender criteria, fees and charges apply. What we can do is prepare the application carefully and match it to lender policy before it’s submitted.
Do you only work in the Hills District?
We’re based in Cherrybrook and many clients are in the Hills District, but we help borrowers across greater Sydney. We have one office and no other branches.
Rates are up. Let’s look at your loan.
Call Rohan directly, or leave your number and he’ll call you back.